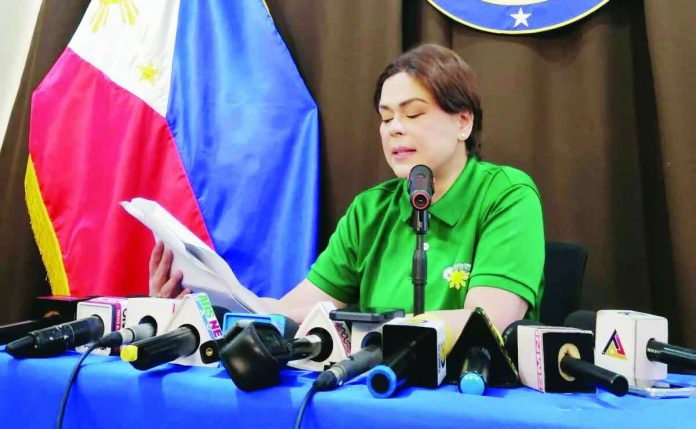
MANILA — Vice President Sara Duterte-Carpio may have received compensation from two government offices simultaneously in 2023, raising questions about a possible constitutional violation after Bureau of Internal Revenue (BIR) records showed she earned P2.36 million from the Davao City government while already serving as the country’s second-highest official.
The disclosure emerged during Duterte-Carpio’s impeachment trial when House prosecutors presented her signed BIR Form 2316, which identified the Davao City government as the source of her compensation income for 2023.
Anne Lorraine Garcia-Marquez, chief of staff of the BIR Office of the Commissioner, confirmed the information contained in the tax document.
“Ang ibig sabihin po ay naka-receive po si VP Sara Duterte ng compensation income from the City Government of Davao…ng taong 2023,” Marquez said.
The revelation immediately raised questions about whether Duterte-Carpio had received compensation prohibited under the 1987 Constitution, which restricts the vice president from receiving additional government compensation or benefits while in office.
House prosecution counsel Erwin Matib questioned the reported payment, particularly because Duterte-Carpio had already assumed the vice presidency on June 30, 2022, after completing her term as Davao City mayor.
The BIR document, however, did not establish when the P2.36 million was actually earned or whether it represented compensation for services rendered before she became vice president.
Prosecutors also examined Duterte-Carpio’s tax declarations for 2021, when she was still serving as Davao City mayor.
The records showed that she declared P2.36 million in compensation income and another P4.65 million under the category of sales, revenues, receipts and fees.
Marquez pointed out that the P4.65 million exceeded Duterte-Carpio’s declared compensation income for that year.
“Based po dito sa BIR records, mas malaki po ‘yung sa practice of profession. Or ‘yung nakalagay sa sales, revenues, receipts, fees,” she said.
Marquez explained that Duterte-Carpio’s BIR registration identified her as a professional engaged in legal activities, suggesting a possible connection between the declared amount and the practice of law.
However, she acknowledged that the tax document itself did not explicitly identify the P4.65 million as income derived from professional practice.
Defense counsel Kristine Ferrer challenged the prosecution’s interpretation, stressing that the document merely classified the amount as “sales, revenues, receipts, fees” without specifying that it came from legal services.
The prosecution nevertheless questioned whether Duterte-Carpio had engaged in professional activities while serving as Davao City mayor.
It cited Section 90 of the Local Government Code, which prohibits local chief executives from practicing their profession or engaging in another occupation during their incumbency.
The 2021 financial declarations, however, were not presented as a separate impeachment charge and fell outside the period covered by the current proceedings.
The prosecution’s examination of the BIR records focused on two issues: the reported P2.36 million in compensation from Davao City in 2023, when Duterte-Carpio was already vice president, and the possible nature of her additional income in 2021, when she was still mayor.
While the records established the amounts declared in her tax documents, they did not conclusively determine whether the payments constituted violations of constitutional or statutory restrictions.
The disclosures are expected to draw further scrutiny as prosecutors seek to establish whether Duterte-Carpio complied with laws governing government compensation and outside professional activities.
The defense, meanwhile, has disputed the prosecution’s interpretation of the tax records, underscoring the need to establish the actual nature and timing of the reported income before drawing conclusions about possible wrongdoing./PN